
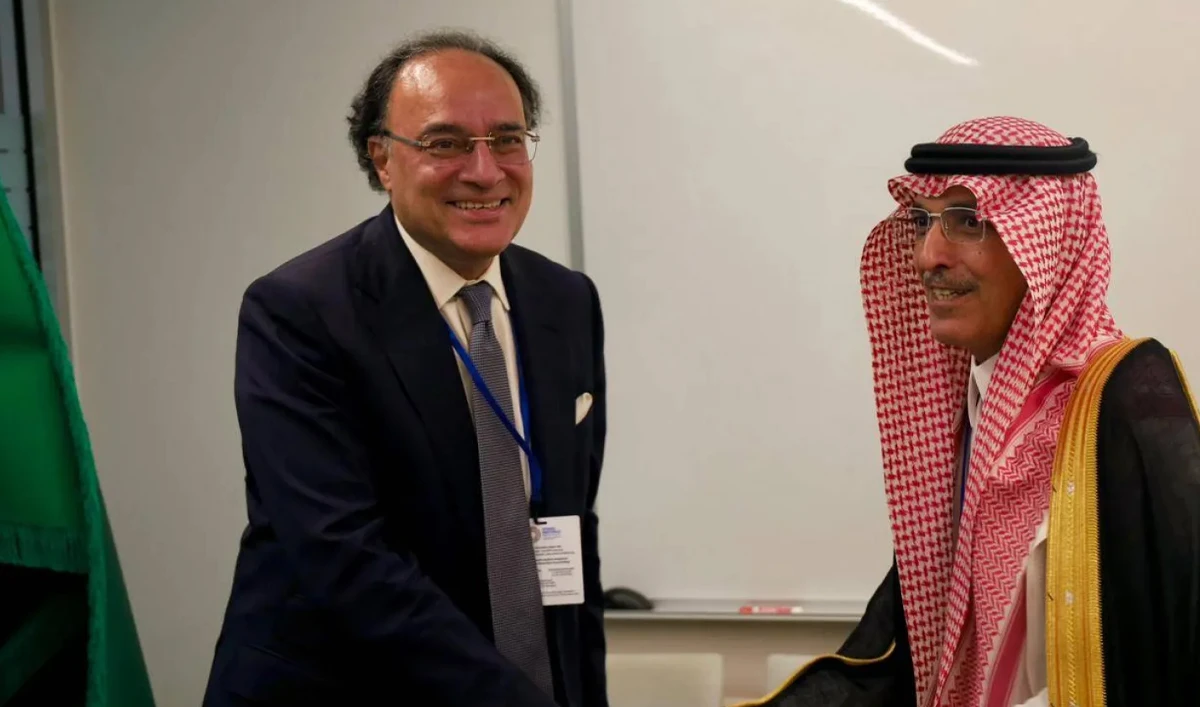
ISLAMABAD: Saudi Arabia has extended the maturity of an additional $3 billion deposit placed with Pakistan for a “reasonable period”, Finance Minister Muhammad Aurangzeb confirmed on Wednesday, providing further financial support as Islamabad works to manage its external debt obligations and strengthen foreign exchange reserves.
Speaking to journalists, Aurangzeb confirmed that the Kingdom had agreed to extend the deposit when asked whether the additional financial facility had been rolled over.
“Yes, its term has been extended. It has been extended for a reasonable period,” the finance minister said.
The latest extension adds to Saudi Arabia’s financial support for Pakistan, which includes an existing $5 billion deposit with the State Bank of Pakistan (SBP). That facility has already been extended until 2028.
Saudi Arabia had committed an additional $3 billion in financial support to Pakistan in April 2026. The subsequent agreement between the Saudi Fund for Development and the State Bank of Pakistan provided for an extension of the deposit’s maturity.
The renewed support comes as Pakistan continues efforts to reduce its reliance on short-term external borrowing, meet international debt repayments and maintain economic stability under its $7 billion International Monetary Fund (IMF) programme.
IMF board review expected in December
Aurangzeb also confirmed that the IMF Executive Board is expected to review Pakistan’s $7 billion programme in December. However, he did not provide a specific date for the meeting.
Pakistan reached a staff-level agreement with the IMF in October on the fourth review of its Extended Fund Facility (EFF) and the third review of its Resilience and Sustainability Facility (RSF).
The agreement remains subject to approval by the IMF Executive Board. Successful completion of the reviews would make approximately $1.2 billion available to Pakistan under the two arrangements.
The government is also working to reduce the cost of external debt servicing through longer-term financing arrangements.
Addressing a Senate committee meeting, Aurangzeb said Pakistan aimed to bring its external debt servicing down to $3.5 billion in the next fiscal year, compared with an estimated $4 billion in the current fiscal year and $4.5 billion in the previous year.
He said the government intended to replace expensive short-term borrowing with financing carrying longer maturities of five to ten years.
“Our objective is very clear: we do not want to increase our external debt,” the finance minister said.
Pakistan seeks to diversify external financing
Aurangzeb said Pakistan was exploring different financing options, including Eurobonds, Panda Bonds and rupee-linked, dollar-settled bonds, to diversify its sources of external funding.
He said the country had raised $3 billion through an international bond issuance in the first week of September, attracting investor orders worth $6 billion.
The government was also pursuing a proposed $10 billion liquidity support facility from the United States. However, Aurangzeb said Pakistan would continue implementing its financing strategy even if the proposed facility did not materialise.
He added that Islamabad was exploring financing arrangements with the US Export-Import Bank and the US Development Finance Corporation to facilitate American exports and investment in Pakistan.
The finance minister also said the government was targeting an improvement in Pakistan’s sovereign credit rating to B-plus by the end of the current fiscal year or early next fiscal year, with a longer-term objective of reaching the double-B category.
Government reports slower growth in public debt
Presenting figures before the Senate committee, Aurangzeb said Pakistan’s public debt-to-GDP ratio had declined to 68.6 percent by the end of June 2026, compared with 75.1 percent in fiscal year 2022-23.
He added that annual public debt growth had slowed to 7.7 percent in the last fiscal year, which he described as the lowest rate in two decades.
According to the finance minister, the government had retired, bought back or exchanged approximately Rs5.9 trillion in debt as part of its liability management strategy.
The amount included Rs3.6 trillion in State Bank debt and Rs2.3 trillion in market debt.
Aurangzeb also said Pakistan’s external debt had increased by approximately $6 billion to $7 billion annually during the previous decade, rising from $45 billion in fiscal year 2015-16 to more than $100 billion.
However, he said the annual increase had slowed to around $1 billion over the past four years.
Pakistan has repeatedly relied on financial assistance and deposit rollovers from friendly countries, including Saudi Arabia, China and the United Arab Emirates, to meet external financing requirements and support its foreign exchange reserves.
The latest Saudi deposit extension provides additional financing stability as Islamabad seeks to reduce refinancing risks, improve its debt profile and maintain progress under the IMF-supported economic programme.
